🏠 Mortgage Calculator
Estimate your full monthly housing payment (PITI): principal, interest, property tax, homeowner's insurance, private mortgage insurance and HOA dues.
Also known as: Home Loan · House Payment · Property Tax · Mortgage Payment · Mortgage Loan Calculator · Simple Mortgage Calculator · Mortgage Rate Calculator
Loading calculator…
⚑ Report a problem with this calculator
How to use the Mortgage Calculator
- Enter your values in the fields above — the defaults show a worked example.
- The result updates instantly as you type; change any input to compare scenarios.
- Copy or share the result, or open a related calculator below.
How it's calculated
Principal & interest = L × r ÷ (1 − (1 + r)−n). Total monthly = P&I + property tax ÷ 12 + insurance ÷ 12 + PMI + HOA. PMI applies while the loan-to-value ratio is above 80%.
Frequently asked questions
What is PITI?
When does PMI stop?
Is the Mortgage Calculator free?
How accurate is the Mortgage Calculator?
Can I use the Mortgage Calculator on my phone or offline?
Read more about the Mortgage Calculator
What makes up a mortgage payment
Lenders often call the monthly payment PITI: principal, interest, taxes and insurance. Principal and interest are fixed for the life of a fixed-rate loan and come from the amortization formula. Property tax and homeowners insurance are usually collected into an escrow account and change when your tax bill or premium changes. With less than 20% down on a conventional loan you also pay private mortgage insurance (PMI), and in many communities a homeowners association (HOA) fee. The calculator shows each piece so you can see which ones you can influence.
Read more
How amortization works
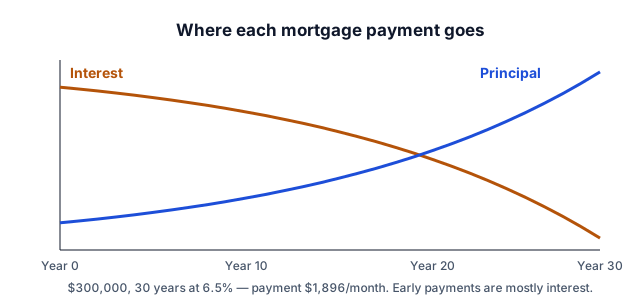
Each month, interest is charged on the balance you still owe: balance × annual rate ÷ 12. Whatever is left of the payment reduces the balance. Because the balance is largest at the start, early payments are mostly interest — on a $300,000 loan at 6.5%, the first payment of about $1,896 includes roughly $1,625 of interest and only $271 of principal. The split flips around year 19, and the final payments are almost all principal. The schedule below the result shows this month by month.
Worked example
| Home price | $375,000 |
| Down payment (20%) | $75,000 |
| Loan | $300,000 |
| Rate / term | 6.5%, 30 years |
| Principal & interest | $1,896.20 |
| Property tax (1.1%) | $343.75 |
| Insurance ($1,800/yr) | $150.00 |
| Total monthly payment | $2,389.95 |
| Total interest over 30 years | $382,633 |
How much house can you afford?
A common guideline is the 28/36 rule: keep housing costs (PITI) under 28% of gross monthly income and all debt payments under 36%. Many lenders approve up to 43%–50% debt-to-income, but a payment that fits the bank’s limit may not fit your budget once you add maintenance (often 1%–2% of the home’s value a year), utilities and savings goals. Use the home affordability calculator to work backwards from your income.
Ways to lower your payment or total cost
- Bigger down payment — reduces the loan and removes PMI at 20%.
- Shorter term — a 15-year loan has a higher payment but usually a lower rate and far less total interest.
- Buy down the rate — discount points cost about 1% of the loan each; see the points break-even calculator.
- Extra payments — even $100–$200 a month can cut years off the loan; try the mortgage payoff calculator.
- Shop lenders — rate quotes on the same day can differ by 0.25%–0.5%, worth tens of thousands over the loan.
Common mistakes
Comparing loans by monthly payment alone hides differences in fees and total interest — compare the APR and the total cost. Forgetting property tax and insurance can understate the real payment by 20% or more. And remember that PMI on a conventional loan can be cancelled once you reach 20% equity, while FHA mortgage insurance usually lasts for the life of the loan if you put down less than 10%.
Fixed-rate vs adjustable-rate (ARM)
A fixed-rate mortgage keeps the same interest rate and principal-and-interest payment for the whole term. An adjustable-rate mortgage (for example a 7/6 ARM) has a fixed rate for the first seven years, then adjusts every six months based on an index plus a margin, within caps. ARMs usually start 0.5–1 point lower, which can make sense if you expect to sell or refinance before the fixed period ends — but the payment can rise sharply later. This calculator models fixed-rate loans; for an ARM, run it at the start rate and again at the maximum capped rate to see the range.
Conventional, FHA, VA and USDA loans
- Conventional — 3%–20%+ down, PMI below 20% that can be cancelled at 20% equity, best for credit scores of about 680+.
- FHA — 3.5% down with a 580 score, upfront and annual mortgage insurance; see the FHA calculator.
- VA — 0% down for eligible veterans, no monthly mortgage insurance, a one-time funding fee; see the VA calculator.
- USDA — 0% down in eligible rural areas with income limits; see the USDA calculator.
Closing costs to budget for
On top of the down payment, buyers typically pay 2%–5% of the loan in closing costs: lender origination and underwriting fees, appraisal, title insurance, recording fees, prepaid interest and initial escrow deposits for tax and insurance. On a $320,000 loan that is roughly $6,400–$16,000. Ask lenders for a Loan Estimate — a standardized three-page form that makes offers easy to compare line by line.
When to use the Mortgage Calculator
Use the Mortgage Calculator for monthly mortgage payment with property tax, home insurance, PMI and HOA, plus an amortization schedule. It is one of 111 free finance calculators, and pairs well with the Home Affordability Calculator, Refinance Calculator, Amortization Calculator and EMI Calculator.
Tips for accurate results
Use the rate and fees from your actual offer or statement rather than an advertised rate, run a best case and a worst case, and remember that taxes, insurance and fees can change the real cost. Results are estimates, not financial or tax advice.
Sources and review
Sources:
- Consumer Financial Protection Bureau
- Federal Reserve — consumer resources
- SEC Investor.gov — financial tools
Every calculator is checked against published reference values before release and re-reviewed when laws, rates or guidelines change. Read our methodology and editorial policy. Found a problem? Report it — we fix errors quickly.
Mortgage payment by loan amount
How much house can I afford?
More Finance Calculators
Popular calculators
Results are estimates for information only and are not financial or tax advice. Calculations run privately in your browser.